Buy a house with zero down. Not a typo.
The USDA loan is the one almost nobody talks about: no down payment, no private mortgage insurance, and rates that are usually lower than conventional or FHA. If you are open to living a little outside the major metro, this could make buying far more doable than you think.
Zero down, no PMI, and whole neighborhoods you would never guess qualify.
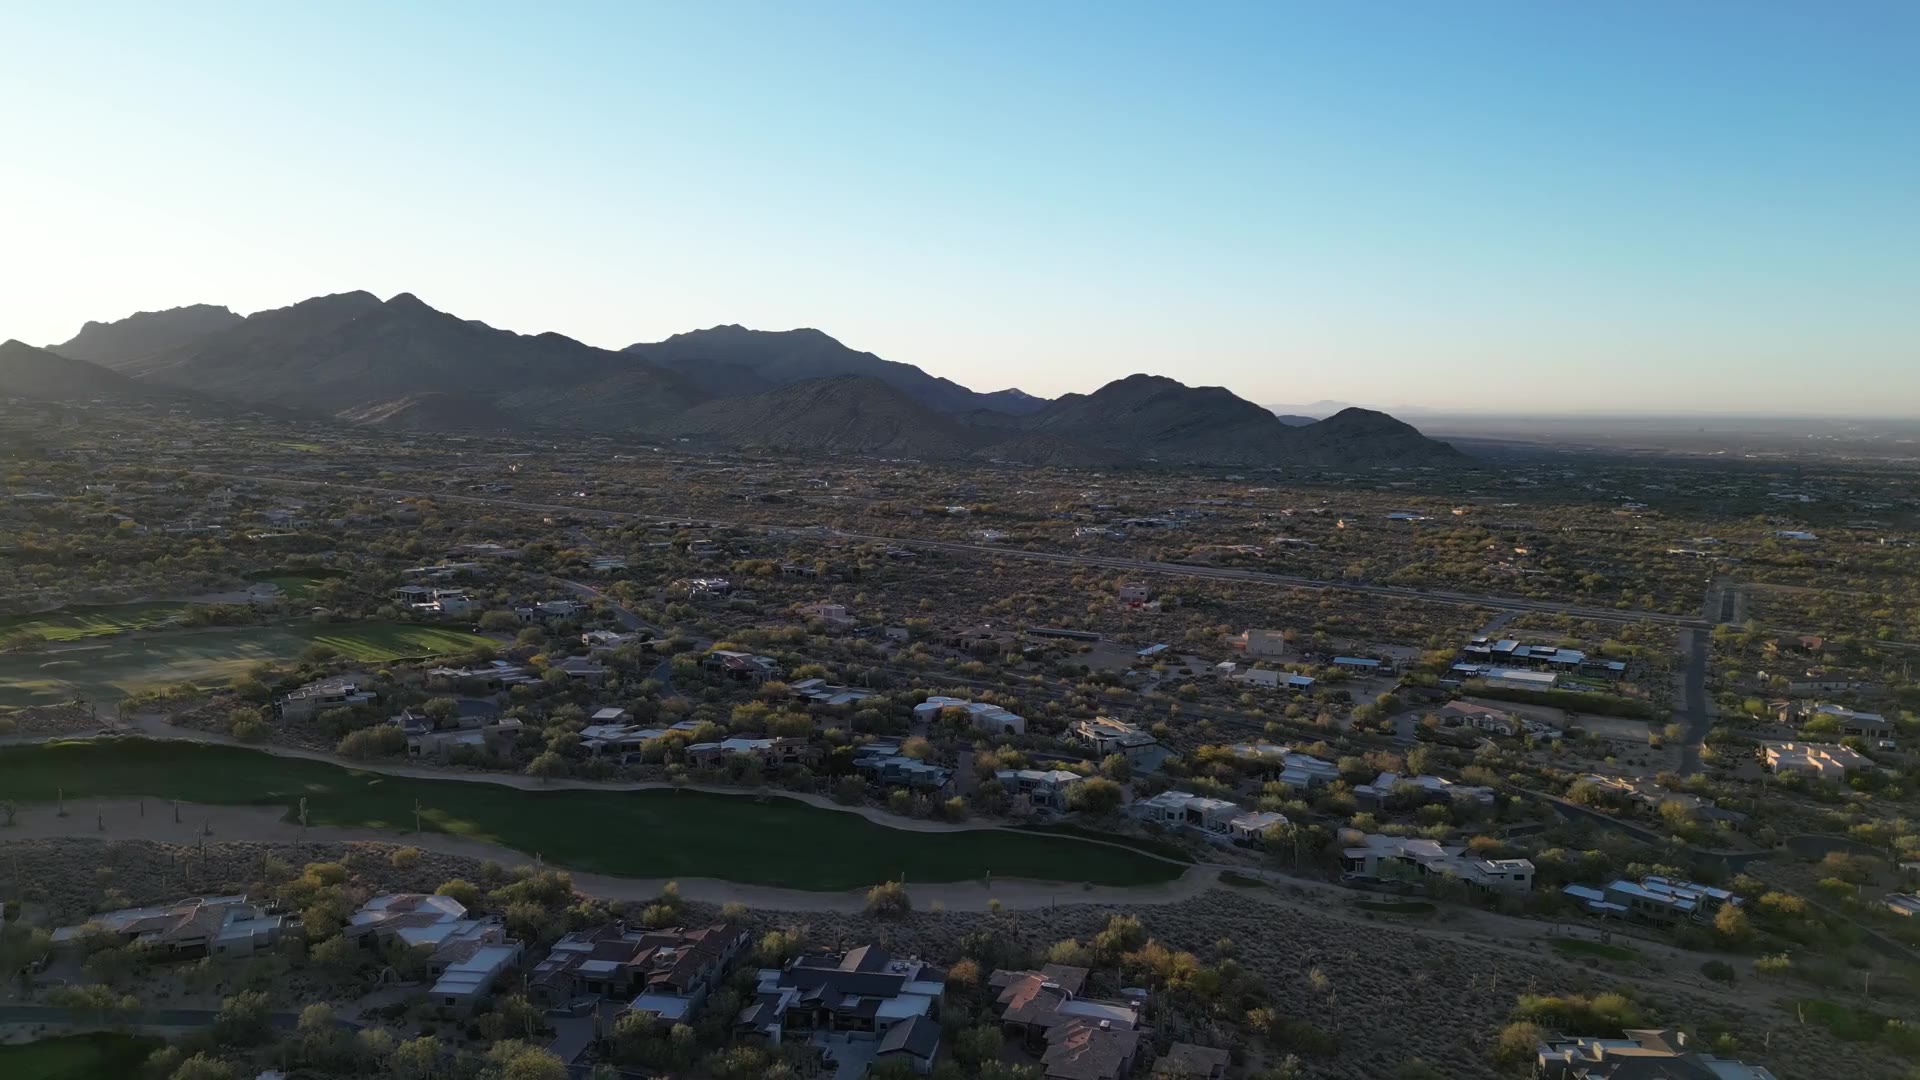
Most people hear "USDA" and picture farms or a cabin in the woods. In reality, entire suburban neighborhoods qualify, sometimes just 20 or 30 minutes outside a big city. Erick recently helped a client buy a home about 20 minutes outside of town with zero down; they had no idea they could even qualify. If your household income is in the moderate range and you would rather not pay mortgage insurance, this loan is a hidden gem.
Who it fits
- Buyers looking a little outside the major metro areas
- Households with moderate income (within the USDA limit for the area)
- Buyers who do not have a down payment saved
- Anyone who would rather not pay private mortgage insurance
- First-time and repeat buyers purchasing a primary residence
Let’s find the right fit.
Apply now or talk through your options with Erick.
Why borrowers choose USDA loans.
Zero down payment
Finance 100% of the purchase price. No down payment, and closing costs can often be covered by seller credits or gift funds.
No private mortgage insurance
USDA uses a modest guarantee fee (1% upfront, which can be financed, plus a small annual fee) instead of PMI, so the monthly payment usually comes in lower than FHA.
Lower rates
Because the loan is backed by the USDA, rates are usually lower than conventional or FHA for the same borrower.
Suburbs qualify
Eligibility is by address, not by how rural it feels. Many growing suburbs 20 to 30 minutes outside Phoenix are on the map. Erick checks your address in minutes.
Flexible credit
Scores of 640 and up get streamlined approval; lower scores are reviewed case by case with compensating factors.
Honest eligibility check
Erick confirms the property area and your household income before you fall in love with a house, so there are no surprises.
Typical requirements
 Property in a USDA-eligible area (Erick checks the address for you)
 Household income within the USDA limit for the county, typically up to 115% of the area median
 Primary residence only; no second homes or rentals
 Credit score of 640 or higher for streamlined approval; lower reviewed case by case
 U.S. citizen, permanent resident or qualified alien
 Stable, documented income and a debt-to-income ratio within program limits
Guidelines vary by lender, program and property. Erick will confirm exact requirements for your file.
How it works
Quick call.
Ten minutes on the phone. You tell Erick the goal, he tells you the realistic options.
Pre-approval.
Send documents through a secure link. Most pre-approvals are issued the same day.
Lock and process.
Rate locked, file submitted, updates in plain English every step.
Close.
Sign with a remote online notary where available, or in person. Keys in hand.
USDA loans FAQ
Does my area really qualify? I am not in the country.
Probably more likely than you think. Whole suburban neighborhoods 20 to 30 minutes outside a major city are eligible. Send Erick the address and he will check it the same day.
Is there really no down payment?
Correct. USDA loans finance 100% of the purchase price. You may still have closing costs, which can often be covered by seller credits, gift funds or assistance programs.
What replaces mortgage insurance?
A USDA guarantee fee: 1% upfront, which can be rolled into the loan, plus a 0.35% annual fee paid monthly. It is typically much cheaper than FHA mortgage insurance.
What is the income limit?
It depends on the county and household size, but it is generally up to 115% of the area median income. Many two-income households still qualify. Erick runs the numbers before you apply.
Can I use a USDA loan to refinance?
Yes. If you already have a USDA loan, the USDA Streamlined-Assist refinance can lower your rate with minimal paperwork.
Ready to talk numbers?
Call, email or send a quick message. Erick answers questions directly and tells you what fits, and what does not.