One broker. 170+ lenders. The right fit for you.
Erick Martinez shops more than 170 lenders to find the right loan at the right price, whether you are buying your first home, refinancing, investing or exploring a reverse mortgage. Straight answers, fast closings, one point of contact.
Erick Martinez · NMLS #1971229 · West Capital Lending NMLS# 1566096
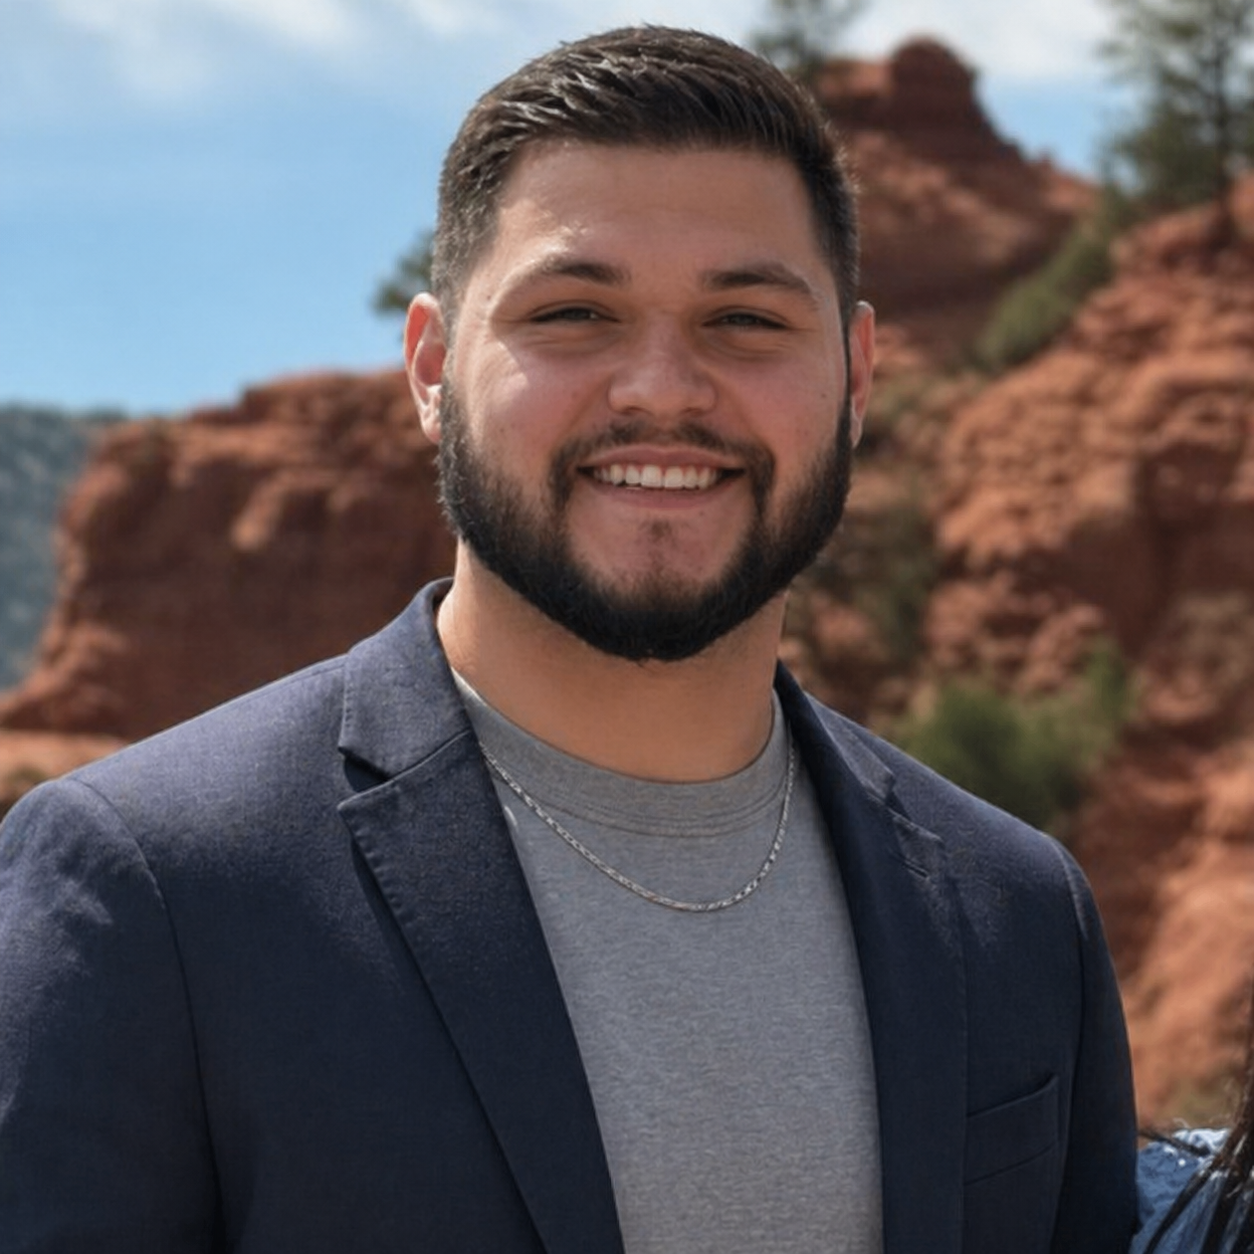
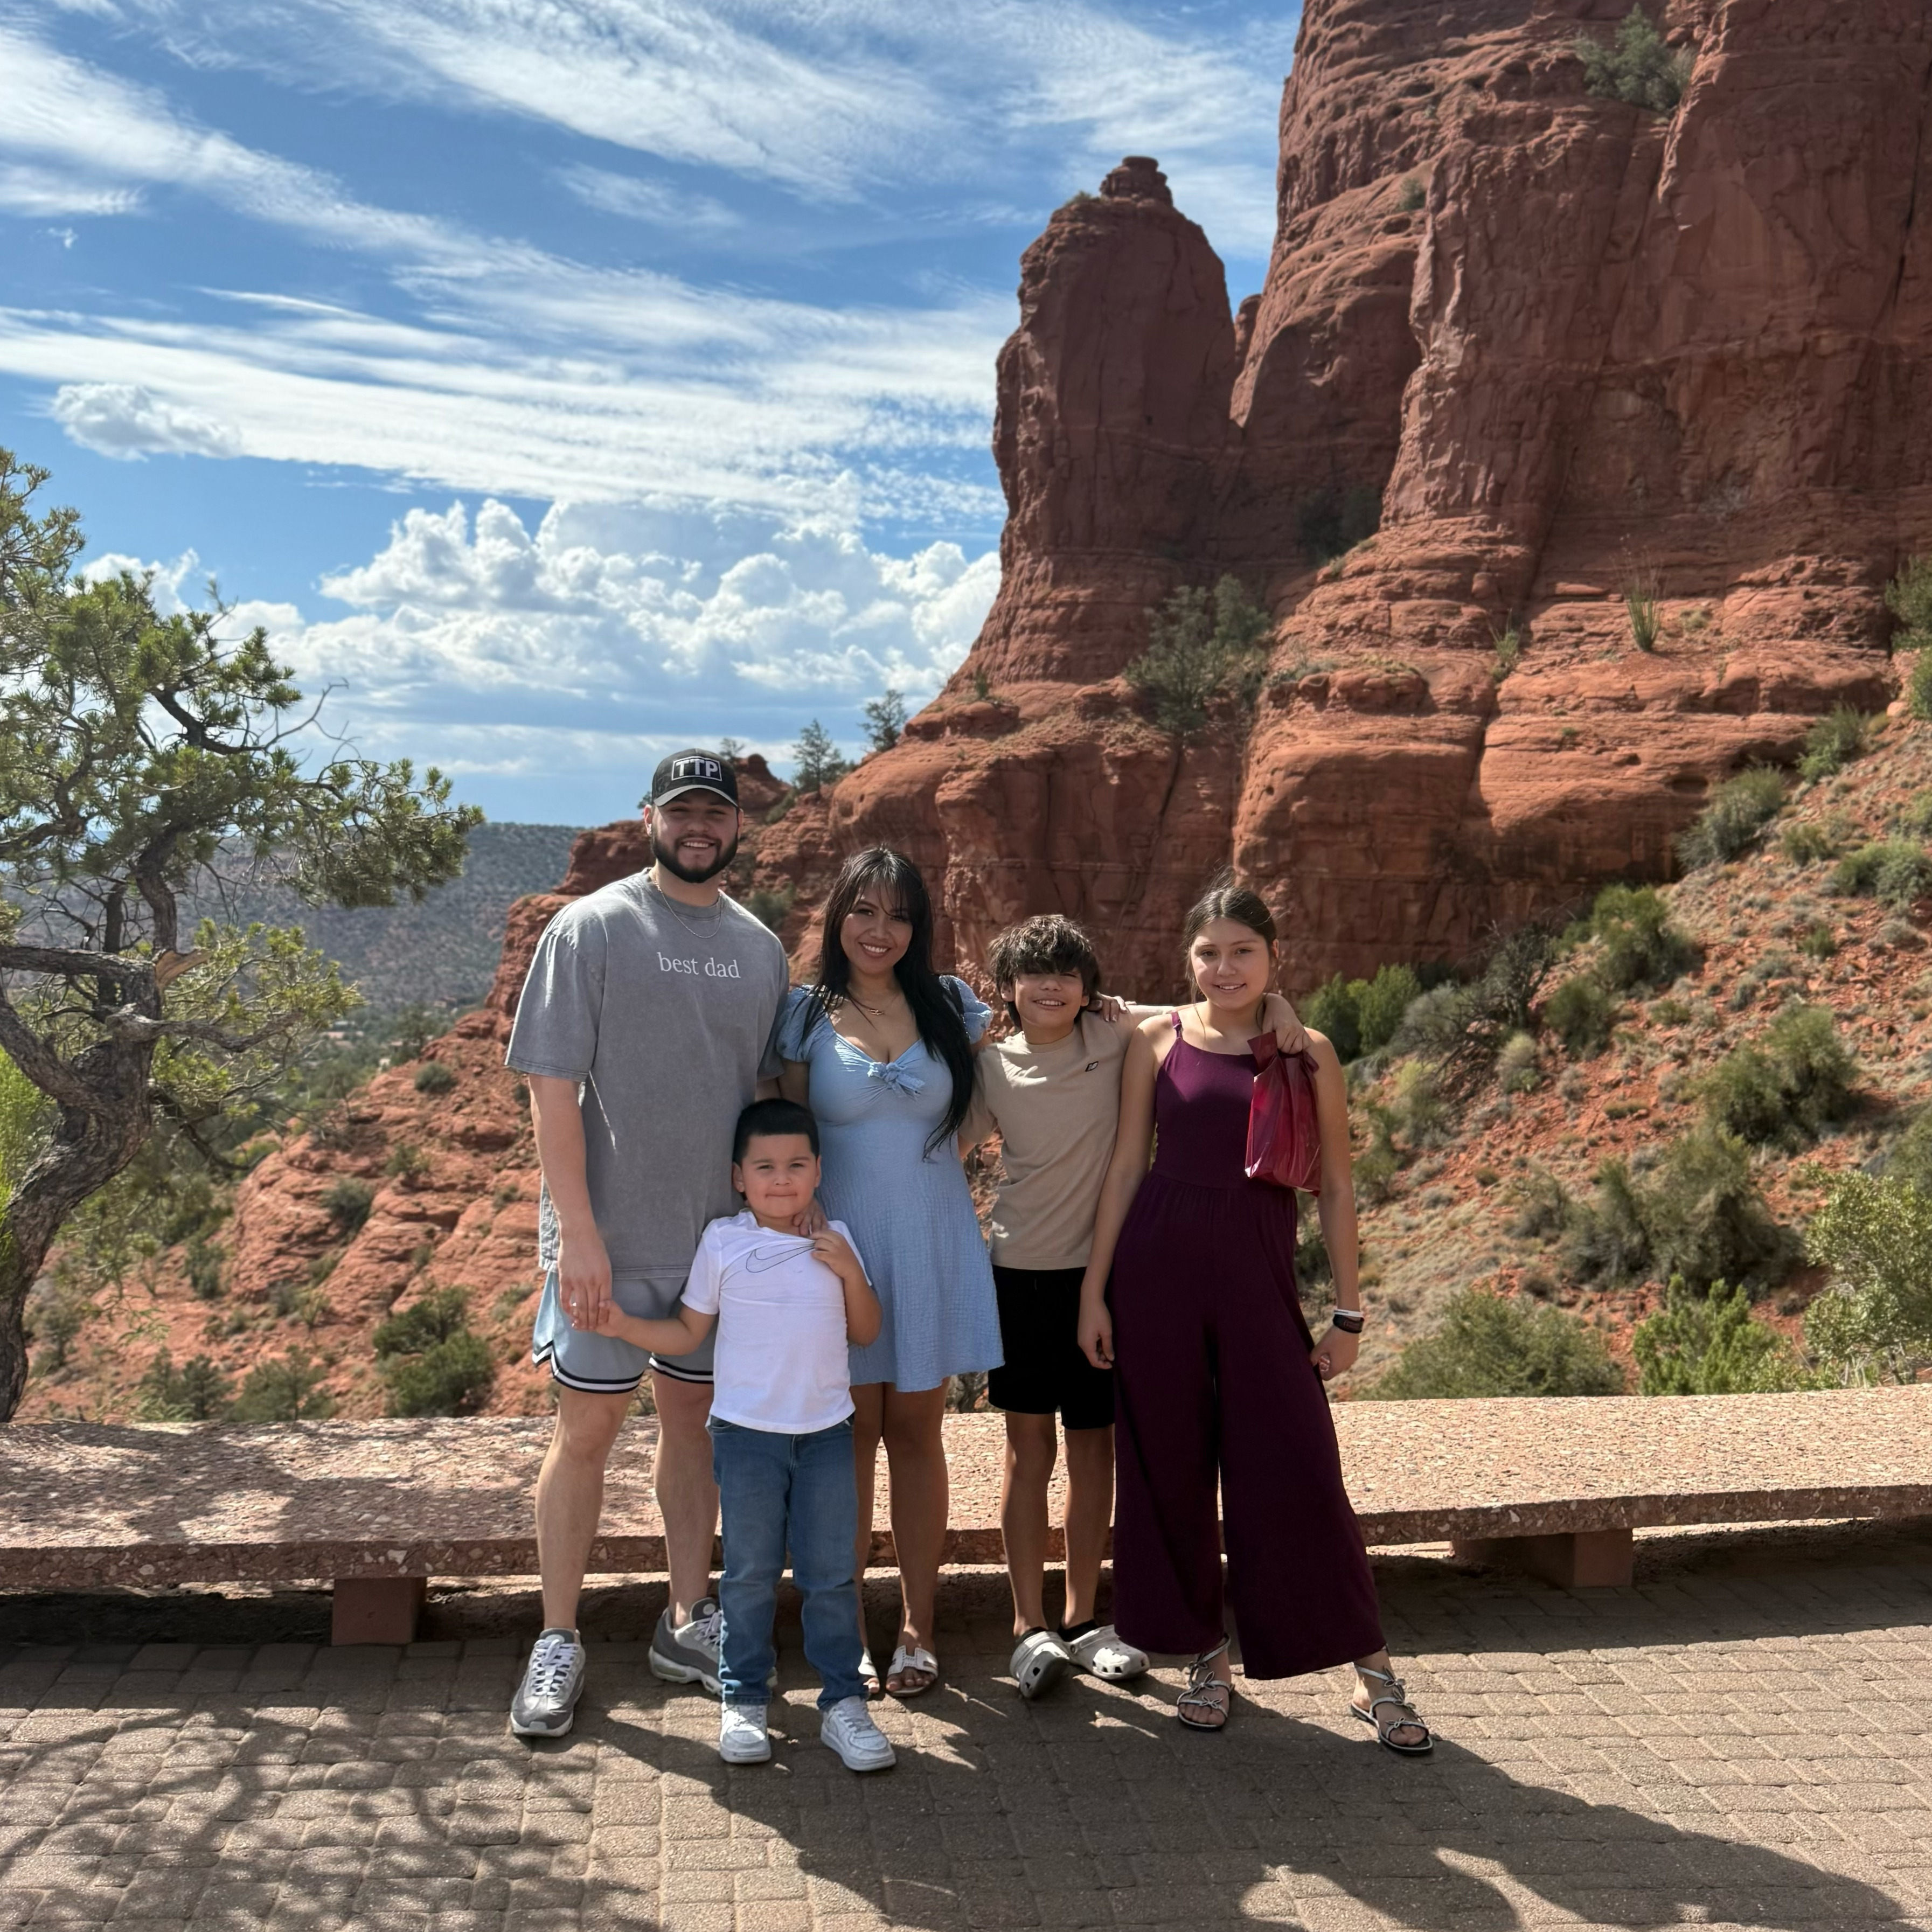
West Valley roots. Family first. No pressure.
Erick grew up in the West Valley and has worked in mortgage and real estate since 2018, covering origination, processing, underwriting and closing. He has seen every side of a file, which is why his approach is low pressure: clear answers, a solid plan, and the truth about a deal even when it is not what you hoped to hear.
Outside of work he is a husband and father of three. Most weekends are spent with family.
Meet Erick in a few minutes.
How a broker with 170+ lenders works, what to expect on your first call, and why the right fit matters more than any single rate.
A program for nearly every situation.
Not sure which one fits? Call Erick. Ten minutes is usually enough to know.
Conventional
As little as 3% down, competitive rates, and mortgage insurance that cancels at 20% equity.
Learn more →FHA
3.5% down and flexible credit guidelines for first-time and rebuilding buyers.
Learn more →VA
Zero down and no monthly mortgage insurance for veterans and active-duty service members.
Learn more →Non-QM
Bank statement, DSCR, 1099 and asset-based loans for self-employed borrowers and investors.
Learn more →Interest Only
Lower initial payments for 5 to 10 years with the flexibility to pay principal on your terms.
Learn more →Reverse Mortgage
Homeowners 62+ convert equity into cash flow with no required monthly mortgage payment.
Learn more →Home Equity Investments
Cash from your equity with no monthly payments. Accepts mortgage late payments and can sit in third position.
Subprime Credit & FHA
FHA down to a 500 credit score, plus non-QM programs for recent bankruptcies, foreclosures and late payments.
Digital HELOC
No tax returns or bank statements. Great for self-employed borrowers. Approval in minutes, and it can be in third position.
Not sure which program fits? Start here.
Erick breaks down the main loan programs, who each one is built for, and how he picks the right one from 170+ lenders.
More ways to get cash from your home than you may realize.
A HELOC and a cash-out refinance are not the only options. Depending on your goal and your credit, an HEI or a digital HELOC may fit better, even behind a loan you already have.
No monthly payments
A Home Equity Investment gives you cash now and settles when you sell or refinance. Late payments on your mortgage are not an automatic no.
Self-employed friendly
A digital HELOC verifies income automatically. No tax returns, no bank statements, funding in as few as five days.
Credit challenged
FHA down to a 500 score and non-QM programs for recent credit events. Buy now, refinance when your credit recovers.
Buying a home has more options than most people realize.
Programs and terms vary and depend on eligibility, but these three change what a buyer can do.
Help with upfront costs
Down payment and closing cost assistance programs for eligible Arizona buyers. Availability and repayment terms vary; Erick confirms what you qualify for.
Explore assistance optionsMake a stronger offer
A fully underwritten pre-approval lets some eligible buyers write a cash-like offer that sellers take seriously in a competitive market.
Explore stronger offersBuy before you sell
Move into the next home before your current one sells, depending on eligibility, using equity from the home you already own.
Ask about this optionPrograms and terms vary. This is not a commitment to lend.
A bank can only sell you its own loan. A broker shops for you.
Erick spent five years at Rocket Mortgage as a loan officer and underwriter. He moved to the broker side for one reason: to offer the best option, not just one lender's option.
- Over 170 wholesale lenders competing for your loan
- Underwriter experience means fewer surprises and cleaner approvals
- Programs for W-2, self-employed, investor, veteran and retiree borrowers
- One point of contact from application to funding
- Rates, fees and timelines explained upfront
Backed by a top-ranked broker partner.
West Capital Lending has been Rocket Mortgage's #1 national broker partner for four years running.
Rocket Pro TPO Elite
Elite partner status
Top Mortgage Broker
2020 Rocket Awards
10 Years
Servicing recognition, 2014 to 2023
Company-wide average as of August 2026.
41,000+ company-wide reviews
Explore feedback about West Capital Lending across multiple branches and loan officers.
Read reviews on
Ratings and review counts reflect West Capital Lending company-wide and are reported by the third-party platforms linked above. Individual loan officer results may vary.
From pre-approval to keys, step by step.
Get pre-approved
Income, assets and credit reviewed so your letter means something to a seller.
Make offers
Shop with a real number and a pre-approval that backs your offer.
Offer accepted
The contract sets the key dates. Erick maps the timeline with your agent.
Underwriting
Appraisal ordered, documents verified, conditions cleared one by one.
Final approval
Clear to close once the last conditions are met.
Move in
Sign, fund, and get the keys. Remote online notary where available.
After closing
Rate and mortgage check-ins so the loan keeps working for you.
The loan process, explained in a few minutes.
Erick walks through what happens from application to closing, what he needs from you at each step, and how to keep the file moving.
Pre-approved in as little as 24 hours.
Easy online process
A short questionnaire you can finish on any device, then a secure link for documents.
No credit impact to start
The questionnaire does not pull credit. Authorization comes later, only when you are ready.
Shop with confidence
Get a buying range and a pre-approval letter you can attach to offers.
The 24-hour timeframe depends on a complete application, documents and credit authorization.
Common questions.
How fast can I get pre-approved?
Most pre-approvals are issued the same day you send your documents through the secure link.
Does it cost more to use a broker?
No. Brokers are paid by the lender in most cases, and shopping 170+ lenders typically results in a better rate or lower fees than a single bank can offer.
What credit score do I need?
It depends on the program. FHA goes down to 500 with 10% down, VA can work with scores in the 580s, conventional typically starts at 620, and some non-QM programs accept recent credit events with compensating factors.
Do I have to be a first-time buyer for assistance programs?
No. Many Arizona assistance programs are open to repeat buyers, and not all assistance is a grant; some has repayment or occupancy terms. Erick explains the fine print before you commit.
Does starting a plan approve me?
No. The questionnaire does not pull credit or approve anyone. It gives Erick what he needs to tell you what is realistic, and a separate application follows when you are ready.
Can I get cash from my home without a new monthly payment?
Yes. A Home Equity Investment (HEI) provides a lump sum with no monthly payments and can sit in third position behind your mortgage and HELOC.
I am self-employed. Can I still qualify?
Yes. Bank statement, 1099 and profit-and-loss programs qualify you on how you actually earn, without relying on tax returns.
Which areas do you serve?
Erick is based in Phoenix and serves borrowers throughout Arizona. See the Licensing page for all states where West Capital Lending is licensed.
Let's find your best option.
One call is usually enough to know where you stand. No obligation, no pressure.